Donation qualified appraisal
Qualified appraisals for donated art and antiques.
The $399 donation report is a qualified appraisal. A qualified appraiser prepares and signs it from your photos and records, with the appraiser declaration and identifying number for Form 8283 Section B.
Tax / donation sample
Picasso Madoura ceramic (A.R. 342)
Fair market value from the live tax sample · open the report to inspect it
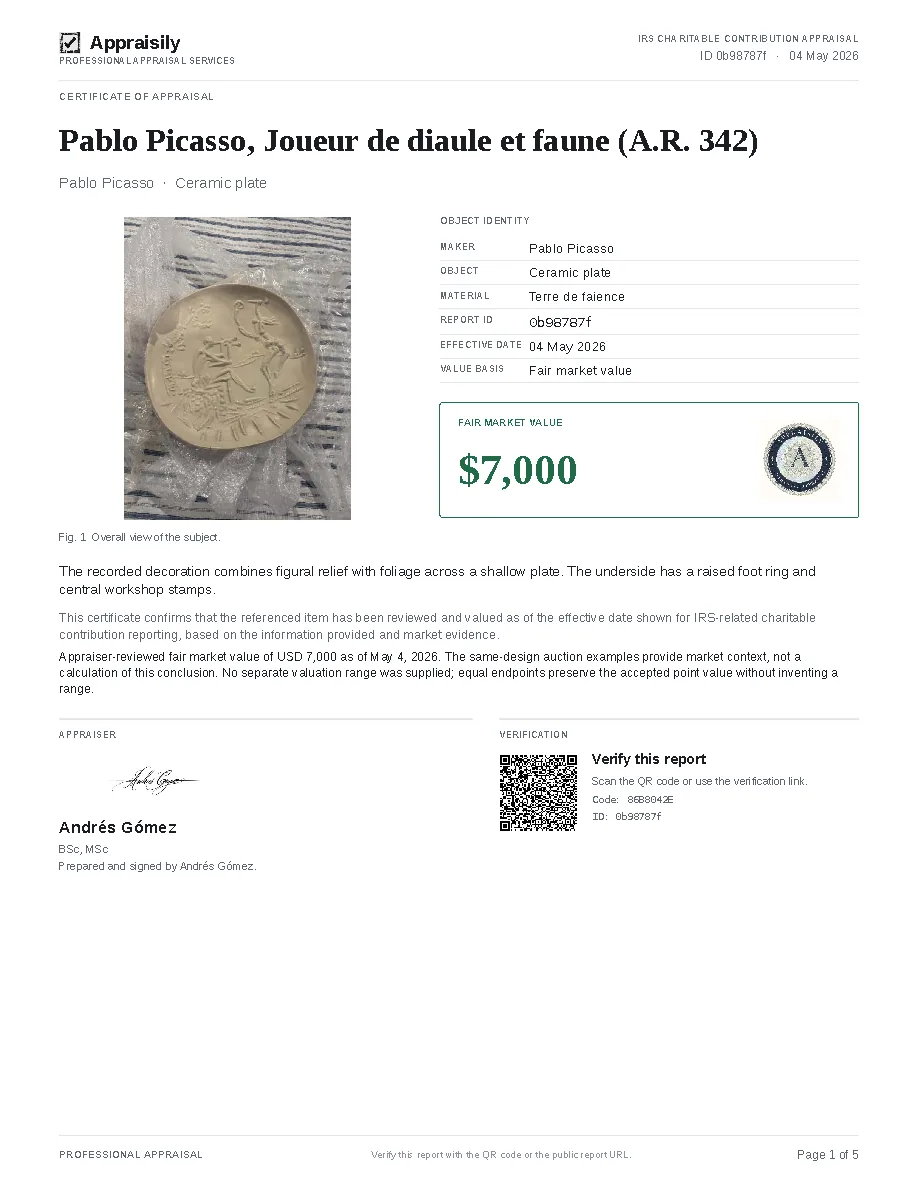
Sample value
$7,000
Report type
Donation / tax
What's in the report
What the IRS still requires
Four rules that stay with your donation.
The report is a qualified appraisal. These IRS rules still apply to your filing. We check the property type and the dates with you before work starts.
- Property type
- The appraiser must be qualified for the type of property. The signed report states the appraiser’s qualifications.
- Timing
- The appraisal must be signed no earlier than 60 days before you donate, and you must have it before your tax return is due (including extensions).
- Form 8283
- You file Form 8283 with your return. Section B applies when you claim more than $5,000 for an item or a group of similar items. The qualified appraiser signs Part IV; the charity signs Part V.
- Art of $20,000 or more
- Attach a complete copy of the signed appraisal to your return, and keep a good photo of the item in case the IRS asks for it.
Your tax adviser decides how to file, and the charity signs its own part of Form 8283. When an item needs an onsite or differently credentialed specialist, we say so before work starts route, we say so and you can find an independent appraiser in the FAIR directory — an independent registry, not an Appraisily referral channel.
Sample PDFs
See the report format before you start.
This is the donation report. The sample shows the format, not a value or approval for your item.
Appraisal report
Tax / donation report
Includes
- Fair market value framing
- Form 8283 support
- Prepared for tax or donation use
Need a different use? See all sample reports.
What to send
Send what you have. We flag what is missing.
Upload the photographs and records you already have. We collect the donation details the IRS asks for before the report is signed. Your tax adviser keeps filing decisions.
Item photographs
One clear photo of the front is all we need to start. Optional, but helpful: the back, signatures or marks, visible damage, and a scale or dimensions.
Ownership and condition records
Send receipts, provenance, prior appraisals, condition notes, inventory lists, or donor acknowledgments if you have them.
Donation context
Share the intended donation, effective date, property location, known deadlines, and any questions your CPA or attorney has raised.
Donation FAQ
Common questions before starting.
If the donation is real and you need the filing path to be cleaner, these are the usual questions.
What is USPAP, and do you claim it?
USPAP is a set of professional standards for appraisers — not a consumer badge on a $59 PDF. We sell a signed photo report. We do not claim USPAP certification. Courses belong at The Appraisal Foundation, ASA, ISA, or AAA; we do not sell continuing education.
Is the $399 donation report a federal qualified appraisal?
Yes. The $399 donation report is a qualified appraisal, prepared and signed by a qualified appraiser, with the appraiser declaration and identifying number for Form 8283 Section B. It must be signed no earlier than 60 days before you donate, and you must have it before your tax return is due. You file Form 8283, and for art of $20,000 or more you attach the full signed appraisal. If you claim $5,000 or less, the IRS does not require a qualified appraisal; you get the signed report for Form 8283 Section A. We do not give tax advice or promise that the IRS will accept the deduction or the value.
Can I use Instant Screener or the $59 report for a deduction?
No. Instant Screener is unsigned. The $59 records report is the wrong report for a CPA donation file. Donation and tax files use $399 case review. We do not give tax advice.
How much does a tax or donation appraisal cost here?
$399 per item for a qualified appraisal, signed by a qualified appraiser. Timing is confirmed after intake; it is not the Standard delivery target.
When do I need a written appraisal for Form 8283?
When you claim more than $5,000 for an item or a group of similar items, Form 8283 Section B applies and you need a qualified appraisal. For art of $20,000 or more you also attach the signed appraisal. Your CPA decides how to file; we do not give tax advice. See /donation.
Is donation fair market value the same as insurance replacement value?
No. Donation work uses fair-market-value concepts for the stated contribution context. Insurance work documents replacement-value needs for an insurer review. One purpose should not be relabeled as the other. A free auction evaluation is the wrong attachment for a CPA.
I typed “USPAP art appraisal online” — what do you actually sell?
A signed photo report. $59 is a records PDF. Insurance is $99 replacement value after you ask the carrier. Donation is a $399 qualified appraisal. We do not claim USPAP certification or sell continuing education. USPAP courses live at The Appraisal Foundation, ASA, ISA, or AAA.
What photos and records should I prepare?
One clear photo of the front is all we need to start. For a donation appraisal we also need the size and a short description (the IRS asks the appraisal to describe the item in detail; we fill what we can from your photo), plus the donation date, the deduction you expect to claim and the property category, because they decide what the report and Form 8283 must include. Optional, but helpful: back, signature, mark or label close-ups, damage, receipts, provenance, prior reports, and your deadline.
How are multiple appraisal items handled?
One order can contain one or many appraisal items. Current checkout applies its configured multi-item pricing rule where eligible; complex, high-value, mixed, or unusual files may require evidence review and a separate quote.
When will timing be confirmed?
Timing is confirmed after case review and varies with complexity, evidence, inspection needs, and current capacity. Do not rely on a fixed hour or day promise unless the assignment confirms one.
What if an onsite inspection or different specialist is required?
Remote evidence may be insufficient when identity, condition, provenance, inspection, or property-specialist questions remain. Use an appropriate independent specialist when the receiving party or assignment requires one. Appraisily does not staff the visit.
Will this hold up when someone asks for proof?
Your report is built so a CPA, donee, or reviewer can follow the comps and understand the number without chasing you for more explanation.
- Report scope
- Visible
- Limitations
- Stated
- Market evidence
- Cited
method and value premise
remote-review and assignment boundaries
relevant comparable references
Visible scope
Assignment-specific scope
Cited support
Comparable evidence
Donation / tax
Intended use stated
Adviser review
Donation qualified appraisal
Defensible
Defensible Documentation
Sources shown
Market-source transparency
Evidence notes
- The report states its method, value premise, assumptions, limitations, and responsible signer.
- The report identifies the market evidence selected for the object and intended use.
- The report names donation or tax as the intended use. It is not a replacement-value insurance report.
- Donation appraisals are qualified appraisals signed by a qualified appraiser, with the appraiser declaration for Form 8283 Section B. Not tax advice.
- The report explains comps, assumptions, and limiting conditions so the number is easier to defend.
- Relevant auction and market references should be cited so another reader can inspect the evidence path.
Ready to get your report started?
Start with a few photos. We handle the research.
A qualified appraisal is $399 per item. Upload what you have; we confirm the property type and the dates with you before work starts.
Start with a $59 signed appraisal
Get a signed value for one item first. If your tax adviser then asks for the $399 donation or tax-estate case review on the same item within 30 days, we credit the full $59, so you pay $340 more. Reply to your report email and we send you the checkout link with the credit applied.
The $59 report is a signed record, not a qualified appraisal for a donation; the $399 donation appraisal is, and only it carries the appraiser declaration for Form 8283 Section B. Check filing requirements with your tax adviser.